Bond Details:
|
Ratings
|
AAA (S&P) / AAA (Fitch), both stable
|
|
Form & Type of the Note
|
Reg S, Bearer, New Global Note (no communication with or into the US)
|
|
Pricing Date
|
17 November 2026
|
|
Settlement Date
|
24 November 2026 (T+5)
|
|
Maturity Date
|
24 May 2030
|
|
Size
|
USD 500 million
|
|
Coupon
|
5.000% (Annual)
|
|
Re-offer Spread vs SOFR MS
|
+34 basis points
|
|
Benchmark
|
CT3 (T 4 ⅝ 11/15/29)
|
|
Re-offer Spread vs Benchmark
|
+13.6 basis points
|
|
Re-offer Price / Yield
|
99.764% / 5.022% (Semi-annual) / 5.085% (Annual)
|
|
ISIN
|
XS3576652997
|
|
Joint Lead Managers
|
BNP Paribas, Crédit Agricole CIB, Daiwa Capital Markets, J.P. Morgan
|
Transaction Highlights:
On Tuesday, 17 November 2026, Nederlandse Financierings-Maatschappij voor Ontwikkelingslanden N.V. (FMO), rated AAA/AAA (S&P/Fitch), successfully priced a USD 500 million 3.5-year senior unsecured benchmark at SOFR Mid Swaps plus 34 basis points.
Against a backdrop of heightened market volatility and more cautious risk sentiment, FMO demonstrated strong execution discipline, capitalising on a good issuance window to secure its targeted benchmark size. The successful transaction underscores FMO’s ability to access the USD market in a more selective environment, supported by its strong credit standing and established global investor base.
The transaction marks FMO’s third fixed-rate USD benchmark of the year, following its USD 500 million 5-year bond in March and USD 500 million 2.5-year bond in January.
The issue carries an annual coupon of 5.000% and will mature on 24 May 2030. It was priced at a spread of 34 basis points over SOFR Mid Swaps, equivalent to 13.6 basis points over the CT3 Treasury note. The pricing translates to a re-offer yield of 5.022% on a semi-annual basis and 5.085% on an annual basis.
The mandate was announced on Monday, 16 November at 10:20 CET, alongside Initial Pricing Thoughts (IPTs) levels of SOFR Mid Swaps plus 34 basis points area.
Indications of interest (“IOIs”) exceeded USD 340 million (excluding Joint Lead Manager “JLM” interest), and books officially opened on Tuesday, 17 November at around 9:10 am CET. Price guidance was maintained in line with IPTs at SOFR Mid Swaps plus 34 basis points area.
By 11:00 am CET, orders stood above USD 460 million (excluding JLM interest). At this stage, FMO set the final reoffer spread at SOFR Mid Swaps plus 34 basis points to support further orderbook momentum.
Shortly thereafter, at 12:00 CET, the orderbook was closed with orders in excess of USD 525 million (excluding JLM interest). Allocations were released at 15:35 CET and the deal was priced at 16:20 CET.
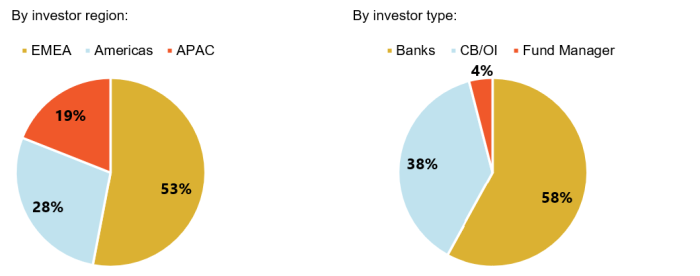
In terms of geographical distribution, the transaction was broadly diversified across EMEA (53%), Americas (28%) and APAC (19%). In terms of investor type, banks were the largest investor component taking 58% of final allocations, supported by strong participation from central banks and official institutions (38%), with fund managers making up the remaining 4%.
The broad and global distribution of this transaction is testament to FMO’s support in the global investor community.
The transaction was led-managed by BNP Paribas, Crédit Agricole CIB, Daiwa Capital Markets and J.P. Morgan.
Distribution Statistics